Which U.S. Banks Accept Non-Resident LLC Owners? (2026 Comparison)
Can you open a U.S. business bank account if you own an LLC from abroad? Compare Mercury, Relay, Bluevine, Wise Business, and Chase in 2026, including country restrictions, EIN document requirements, website rules, and account fees.
- #LLC Banking
- #Non-Resident LLC
- #US Business Bank Account
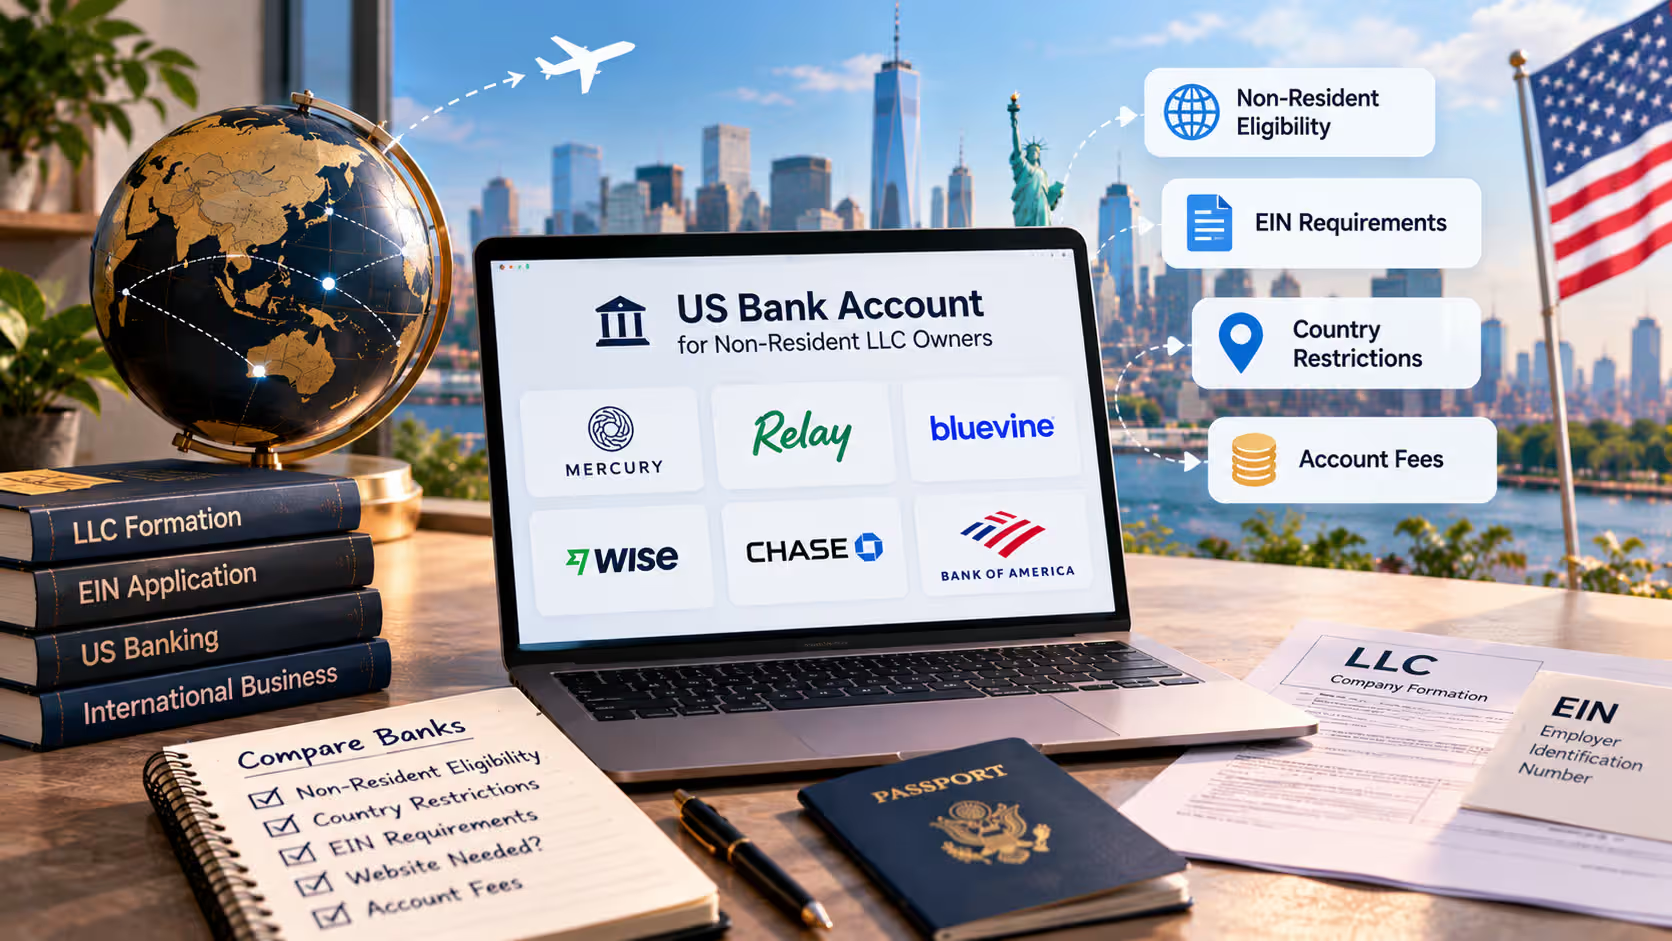
A us bank account for non resident llc owners is possible with some providers, but approval depends on your country, business activity, and identity checks. Mercury, Relay, Bluevine, and Wise Business offer options for some foreign owners; traditional banks may require a U.S. branch visit.
This comparison reviews non-resident eligibility, country restrictions, EIN documentation, website requirements, and published fees. Policies can change, and an application is never guaranteed approval. If you need a US bank account for non resident LLC operations, compare both eligibility and the type of account each provider offers.
Which U.S. Banks Accept Non-Resident LLC Owners in 2026?
Several U.S. banking providers accept applications from some non-resident LLC owners. Mercury, Relay, Bluevine, and Wise Business publish international-owner eligibility information. Chase may be an option if you can meet its branch and identification requirements. Bank of America currently says applicants for its LLC account must be U.S. residents.
Mercury, Relay, Bluevine, and Wise are financial technology or payment providers. They are not all banks. Some banking services are provided by partner banks. Read the account agreement to see which institution holds your funds and what protections apply.
US Bank Account for Non Resident LLC: How to Choose a Provider
People searching for the best banks for non resident LLC owners should compare both banks and financial technology providers. Some options are not banks themselves, and availability depends on where the owner lives and how the LLC operates.
Before choosing a US bank account for non resident LLC ownership, check whether the provider accepts your country of residence, supports your business activity, and can verify your U.S. company address and EIN. The right US bank account for non resident LLC owners is the one that accepts their location and business model, not simply the one with the lowest fee.
2026 Comparison: U.S. Business Accounts for Non-Resident LLC Owners
If you are comparing a US business bank account for non residents, look beyond the provider name. Check the country rules, U.S. business-presence test, identity checks, accepted EIN proof, and total account fees.
This table compares published requirements checked on October 30, 2026. Eligibility is not guaranteed. Each provider reviews the owner, country, and business.
Online Providers for International LLC Owners
| Provider | Accepts non-resident LLC owners? | Country restrictions | EIN letter / proof | Website needed? | Published fees |
|---|---|---|---|---|---|
| Mercury | Yes. U.S.-formed LLCs with current or planned U.S. operations. | Yes. Some countries are blocked. The owner's place of residence matters. | Yes. CP 575, Letter 147C, or an IRS-returned SS-4 is listed. | No. A website can help, but is not required. | $0 monthly fee on the basic plan. |
| Relay | Yes. The LLC must have a U.S. operating presence. Owners must live in supported countries. | Yes. Check Relay's current prohibited-country list. | An EIN and business records are required. Confirm the exact notice format with Relay. | No website requirement is listed. A supported email is needed. | Starter: $0/month. Paid plans and transaction fees may apply. |
Bluevine and Wise Business
| Provider | Accepts non-resident LLC owners? | Country restrictions | EIN letter / proof | Website needed? | Published fees |
|---|---|---|---|---|---|
| Bluevine | Yes. Some foreign owners qualify if they live in a supported country. | Yes. Only residents of listed countries qualify. India is included on the published list; check for updates. | A valid EIN and passport are required. Confirm which IRS EIN proof is accepted. | No general website rule is listed. Be ready to explain the business. | Standard: $0/month. Optional plans and service fees may apply. |
Traditional Banks and Other Account Options
| Provider | Accepts non-resident LLC owners? | Country restrictions | EIN letter / proof | Website needed? | Published fees |
|---|---|---|---|---|---|
| Wise Business | Potentially. Access depends on the owner's country and the services requested. | Yes. USD account details are not available in every country. | EIN and business records are required. More owner checks may apply. | No general website rule is listed. Wise may ask for more business evidence. | $31 one-time fee for U.S. account details. Transfer and FX fees vary. |
Bank of America
| Provider | Accepts non-resident LLC owners? | Country restrictions | EIN letter / proof | Website needed? | Published fees |
|---|---|---|---|---|---|
| Chase | Possible in some cases. A branch visit may be needed. | No public list for this comparison. U.S. sanctions and bank rules apply. | EIN required. Chase may also ask for SSN, ITIN, or foreign tax number. | No general website rule is listed. Business records may be reviewed. | Monthly fee may apply. Waivers and account terms vary. |
| Bank of America | Generally no for applicants living abroad under its published LLC rules. | Published application route requires U.S. residency. | EIN and personal identity details are required. | Not the main issue; residency is the key restriction. | Fees depend on the account and state. |
Fees can add up. The table shows base or setup fees only. Wires, currency exchange, cash deposits, and extra services may cost more. Check the current fee list before you apply.
Mercury: A Common Online Option for Foreign-Owned LLCs
Mercury says owners do not need to be U.S. citizens or residents. The LLC must be formed in the U.S. or a U.S. territory. It must have current or planned U.S. operations and a valid main business address. A registered-agent address, P.O. box, or UPS Store address cannot be used as that main address.
Mercury accepts an international passport for identity checks and lists CP 575, Letter 147C, or an IRS-returned SS-4 as EIN documentation. A website is not mandatory, but Mercury says a web presence can help its team understand the business. Its restricted-country rules are based on where founders or financial controllers live, so check the list before applying.
Official details: Mercury eligibility, Mercury required documents, and Mercury prohibited countries.
Relay: Online Banking With Country and U.S. Presence Checks
Review Relay business banking eligibility before starting an application. In particular, confirm that each owner lives in a supported country and that the LLC can show the required U.S. operating presence.
Relay accepts some U.S. businesses owned by people who are not U.S. citizens or residents. The business needs a U.S. operating presence. Each owner must live in a supported country. Relay may ask about U.S. activity, funds, and countries where the business operates.
Relay's prohibited-country policy applies to owners listed on the application, including beneficial owners. Its Starter plan is listed at $0 per month, while paid plans cost more and transaction fees may apply. Relay is a financial technology company, not an FDIC-insured bank; banking services are provided through its banking partner.
Official details: Relay signup eligibility, Relay prohibited countries, and Relay pricing.
Bluevine: Non-Resident Access From a Published Country List
Bluevine has an application route for some foreign owners of U.S. LLCs and corporations. Applicants need an EIN and a valid passport. They must live in a supported country. Bluevine says eligible foreign owners do not need a U.S. SSN.
Bluevine's published list includes India and several countries in Europe, as well as Australia, Canada, and New Zealand. Do not assume that every country is supported. Check the current list on Bluevine's international-owner page because country eligibility can change.
Official details: Bluevine international-owner eligibility and Bluevine business banking FAQs.
Wise Business: Useful for International Payments, but Not a Traditional Bank Account
Wise Business can help with payments in more than one currency. It is not a bank. Access to USD account details depends on the business and owner's country. Wise also has country limits.
For a U.S. business, Wise asks for the business name, entity type, EIN, registration address, and details about beneficial owners and the account controller. Non-U.S. beneficial owners may be asked for photo identification. The U.S. pricing page lists a one-time $31 fee for account details, plus variable transfer and conversion fees.
Official details: Wise U.S. business verification, Wise USD account detail restrictions, and Wise Business pricing.
Chase: A Traditional Bank Option If You Can Visit a Branch
Chase has ID rules for non-U.S. citizens. It may accept a passport for some non-permanent residents. A business account needs an EIN. Chase may also ask for an SSN, ITIN, or foreign tax number, plus company records.
For an LLC, Chase says the members or managers who need to be present depend on whether the LLC is member-managed or manager-managed. This makes Chase less convenient for an owner who lives abroad and cannot travel to a U.S. branch. Contact the specific branch before making travel plans, and ask what it will accept for your ownership structure and foreign address.
Official details: Chase business account information and Chase account opening guide.
Bank of America: Why It May Not Fit an Owner Living Abroad
Bank of America says LLC account applicants should live in the U.S. It also asks for personal details, including an SSN and date of birth, for applicants and some owners. This may rule it out for owners who live abroad.
If you live outside the United States, do not assume that forming a U.S. LLC alone makes you eligible. Check directly with Bank of America for any policy changes before preparing an application.
Official details: Bank of America LLC application requirements.
Does a Non-Resident LLC Need an EIN Letter to Open a Bank Account?
An EIN for business bank account applications is usually a core requirement for a U.S.-formed LLC. However, providers may differ on which IRS document they accept as proof that the EIN has been assigned.
Most providers require the LLC's EIN, but they do not all publish the same document rules. Mercury specifically lists CP 575, Letter 147C, and the IRS-returned SS-4 as acceptable EIN documents. Relay requires an EIN and business records. Bluevine and Chase require an EIN, but applicants should confirm which proof document the bank will accept.
If your EIN letter has not arrived, ask the provider whether it accepts an IRS verification letter or another official IRS record. Do not upload an SS-4 application draft and assume it proves that an EIN has been assigned. For help with a missing IRS notice, read our EIN delay help guide.
Do You Need a Website to Open a U.S. Business Bank Account?
A website is not a universal requirement, but an online presence can help a provider understand and verify your business. Mercury says a website is not required, although it can help its onboarding team. Relay's published signup checklist asks for a supported email address and business details, not a website. Other providers may ask for additional evidence depending on the business type and risk review.
If you do not have a website, prepare a clear business description instead. Explain what the LLC sells or provides, who its customers are, where it operates, how it earns revenue, and how you expect to use the account. Be truthful and make sure the information matches your formation documents and application.
What Documents Should a Non-Resident LLC Owner Prepare?
Requirements differ, but the following documents are commonly useful when applying for a US bank account for non resident LLC owners:
- State-filed Articles of Organization or Certificate of Formation
- IRS EIN confirmation document, such as CP 575 or Letter 147C where accepted
- Operating Agreement, if requested
- Valid passport for each owner or beneficial owner
- Residential address evidence for owners
- Business operating address and evidence of U.S. business activity, if required
- Business website, online store, contracts, invoices, or other evidence of activity, if available
- Details about source of funds, expected transactions, customers, and countries of operation
Names and addresses should be consistent across your state formation record, IRS EIN record, passport, and bank application. Differences can lead to extra questions or a declined application.
How to Choose the Right Account for Your LLC
- Check your country first. Review the provider's current restricted or supported-country list using your country of residence, not only your citizenship.
- Confirm the business-presence rule. Some providers require evidence of actual or planned U.S. operations, not just a registered agent address.
- Confirm EIN document acceptance. Ask whether CP 575, Letter 147C, or an IRS-returned SS-4 is acceptable before applying.
- Check the website and address rules. Do not use a registered agent address where a provider requires a physical operating address.
- Compare total fees. Include monthly plan charges, wire fees, foreign exchange costs, ATM fees, and incoming payment charges.
- Apply with matching information. Make sure the legal name, EIN, owners, and addresses match the supporting records.
Frequently Asked Questions
Can a non-U.S. resident open a U.S. bank account for an LLC?
Yes, some providers accept eligible foreign-owned U.S. LLCs. Mercury, Relay, Bluevine, and Wise Business publish international-owner options, but each has country, business, and identity requirements.
Which U.S. bank is easiest for a non-resident LLC owner?
There is no provider that is easiest for every country or business. Mercury, Relay, Bluevine, and Wise Business allow some remote applications, but country restrictions and U.S. operating-presence requirements differ. Compare these rules before you apply for a US bank account for non resident LLC operations.
Can I open a U.S. business account without an SSN?
Some providers allow eligible non-U.S. owners to apply without a U.S. SSN. They may instead require a passport, residential address, EIN, and additional identity or business verification.
Does Mercury accept a 147C letter instead of CP 575?
Yes. Mercury lists Letter 147C as an acceptable EIN document. It also lists CP 575 and the IRS-returned SS-4, subject to its review.
Does every provider accept a registered agent address?
No. Address rules vary, and a registered agent address may not satisfy a provider's operating-address requirement. Mercury explicitly says a registered-agent address cannot be used as the principal place of business.
Do I need to travel to the United States to open an account?
Not always. Some fintech providers support online applications from eligible foreign owners. Traditional banks such as Chase may require a branch visit or in-person identity checks depending on the application.
Is Wise Business the same as a U.S. bank account?
No. Wise is a financial technology company, not a bank. It provides multi-currency account services and payment features, and USD account detail availability depends on eligibility and location.
Final Takeaway
A US bank account for non resident LLC owners may be available in 2026, but approval depends on the owner's country, the company's real activity, and the provider's verification rules. Compare Mercury, Relay, Bluevine, and Wise Business first if you need a remote application, and consider Chase if you can meet its branch requirements. Confirm the latest country list, EIN document rules, address requirements, and full fee schedule before applying.
Important: EINNumber.io is a private EIN application assistance service, not a bank, the IRS, or a government agency. Bank and fintech account providers make their own approval decisions. EINNumber.io cannot guarantee account approval.