Foreign Company EIN Case Study: How an Indian Company Applied for a U.S. EIN
Learn how an Indian company may obtain a U.S. EIN for treaty-related tax documentation. This illustrative case study explains the documents, Form SS-4 entries, and application process.
- #Foreign Company EIN
- #Form SS-4
- #India EIN Application
- #U.S. Tax Treaty
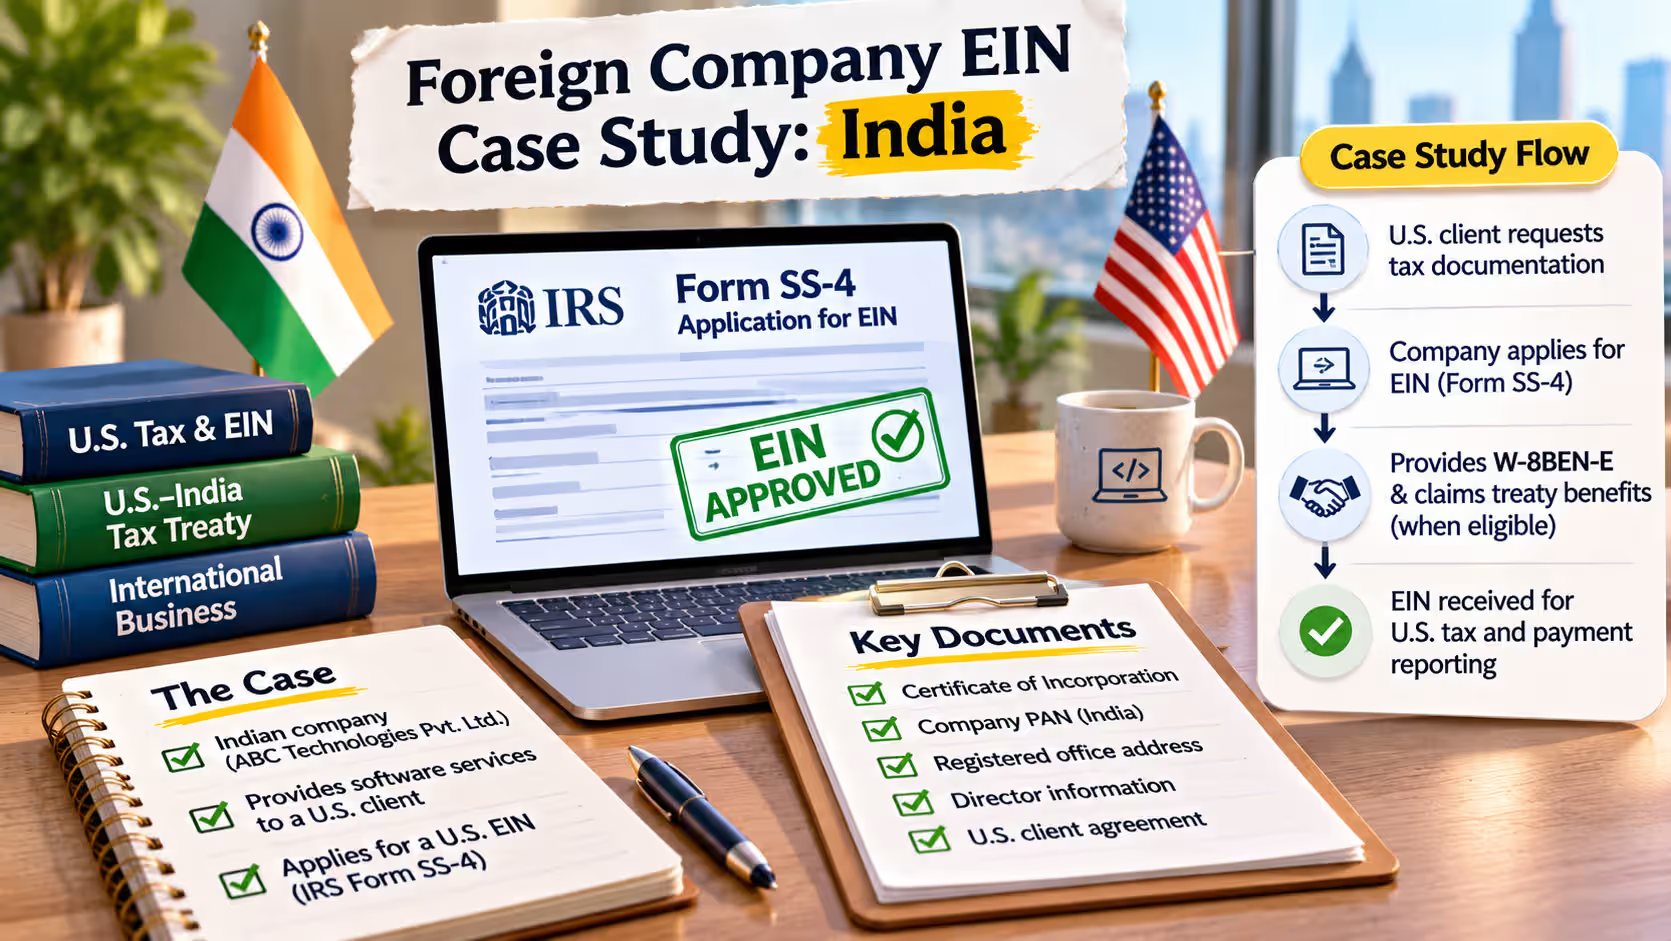
A foreign company EIN case study can help explain how an international business applies for a U.S. Employer Identification Number (EIN). In this example, we look at an Indian company that needs U.S. tax documentation to receive payments from an American client and consider a tax treaty claim.
Important: This is an illustrative case study. The company, application details, and timeline are fictional examples. An EIN does not automatically provide tax treaty benefits. The company must meet the relevant treaty requirements.
1. The Case: An Indian Company Working With a U.S. Client
Imagine an Indian private limited company called ABC Technologies Private Limited. It provides software development and technical services to customers in the United States.
The company signs a service agreement with a U.S. business. Before making payments, the U.S. client asks ABC Technologies for tax documentation.
The client wants to confirm:
- That the company is legally registered in India.
- That it is a foreign business, not a U.S. company.
- Which company owns the income.
- Whether the company can claim any applicable U.S.–India tax treaty benefits.
- Whether the company has a U.S. taxpayer identification number.
The client explains that an EIN may be needed for its payment and tax reporting process. ABC Technologies therefore reviews its U.S. tax documentation requirements before applying.
2. Why Did the Indian Company Need an EIN?
ABC Technologies considered applying for an EIN because its U.S. client requested a U.S. taxpayer identification number for its tax records and withholding documentation.
A foreign company may need an EIN for certain U.S. tax reporting, filing, or withholding purposes. It may also apply for an EIN when a U.S. TIN is required for a particular treaty-related claim.
However, an EIN is only a tax identification number. It does not prove treaty eligibility or automatically reduce U.S. withholding tax.
How Does the U.S.–India Tax Treaty Fit Into the Case?
The United States and India have an income tax treaty. Depending on the income type and the company's circumstances, the treaty may reduce or change U.S. taxation.
For example, the treaty has rules for royalties and fees for included services. The correct treatment depends on the nature of the payment and the treaty's conditions.
The company must also consider whether it is the beneficial owner of the income, whether it is a tax resident of India, and whether it meets any applicable limitation-on-benefits requirements.
Foreign company tax treaty benefits depend on the applicable treaty, income type, tax residency, beneficial ownership, and other eligibility conditions. An EIN alone does not guarantee a reduced withholding rate.
ABC Technologies cannot claim treaty benefits simply because it receives an EIN.
3. Documents the Indian Company Prepared
Before completing Form SS-4, ABC Technologies collected basic company and ownership information. These documents helped the company prepare accurate answers for the IRS.
- Certificate of Incorporation: Evidence that the company is registered in India.
- Company PAN: The Indian tax identification number.
- Registered office details: The company's complete Indian address.
- Director information: Details of the person who manages or controls the company.
- Business activity details: A clear description of the company's services.
- U.S. client agreement: A copy of the agreement explaining the business relationship and expected payments.
- Payment information: Details of the income expected from the U.S. client.
These are practical preparation documents for the example. The IRS does not necessarily require every item to be attached to Form SS-4. The company should follow the current IRS application instructions and keep supporting records available.
4. How the Company Completed Form SS-4
ABC Technologies used Form SS-4, Application for Employer Identification Number, to request its EIN.
The following example shows how an Indian company might prepare the relevant form entries. The correct answers depend on its legal structure and actual tax situation.
Important Form SS-4 Lines for an Indian Company
| SS-4 line | Example information |
|---|---|
| Line 1 | ABC Technologies Private Limited |
| Lines 2–3 | Trade name or care-of name, if applicable |
| Lines 4–5 | Complete Indian mailing and physical address |
| Line 6 | City and state where the principal business is located in India |
| Line 7a | Name of the individual responsible party |
| Line 7b | SSN, ITIN, or EIN if available; otherwise, follow the applicable IRS instructions |
| Line 8 | Answer based on whether the applicant is an LLC |
| Line 9a | Choose the appropriate entity classification, such as corporation, based on the actual entity |
| Line 10 | Other — For Tax Treaty Purposes Only, if this is the actual reason for applying |
| Line 11 | Date the business started or acquired, as applicable |
| Lines 12–17 | Answer according to the company's actual accounting, employee, and business information |
| Line 18 | Indicate whether the company has previously received an EIN |
Choosing the Correct Responsible Party
The responsible party must generally be a real individual who owns or controls the company. A nominee or outside formation agent should not be listed simply because they helped prepare the application.
For certain foreign entities applying solely for a treaty-related purpose or another listed withholding purpose, the IRS has special instructions for Line 7b. If the entity has no U.S. tax return filing requirement and no SSN or ITIN, it generally enters "N/A" on Line 7b under those specific instructions. This is not a general rule for every foreign company.
The phrase "For Tax Treaty Purposes Only" on Line 10 should only be used when it accurately describes the reason for applying. A company applying for another reason should select the appropriate purpose.
In the specific treaty-only situation described in the IRS instructions, Lines 11–17 may need to be marked "N/A" if the foreign entity has no U.S. tax return filing requirement. The company should check the current instructions before submitting the form.
Read our guide to the EIN responsible party for more information.
5. Foreign Company EIN Case Study: How the Indian Company Applied
Because ABC Technologies had its principal place of business in India, it could not use the IRS online EIN application. International applicants in this situation can apply by telephone, fax, or mail.
This Indian company U.S. EIN application example shows how a business based in India can prepare Form SS-4 and choose the correct IRS application method.
Option 1: Apply by Phone
The authorized company representative can call the IRS international EIN telephone line at 267-941-1099. This is not a toll-free number.
The current IRS instructions list the phone service hours as Monday through Friday, 6:00 a.m. to 11:00 p.m. Eastern Time. The person calling must be authorized to receive the EIN and answer questions about Form SS-4.
Option 2: Apply by Fax
The company can complete and fax Form SS-4 from India to:
304-707-9471
The company should include a fax number so the IRS can return the EIN information by fax. The IRS says fax applications are generally processed within four business days, although delays can happen.
Option 3: Apply by Mail
The company can also send the completed and signed Form SS-4 to:
Internal Revenue Service
Attn: EIN International Operation
Cincinnati, OH 45999
USA
The IRS advises international applicants to allow approximately four weeks for a mailed application. Processing times may change.
6. Example EIN Application Timeline
Here is an illustrative timeline showing how ABC Technologies might organize its application. These are planning examples, not a record of an actual IRS approval.
| Stage | Example timing |
|---|---|
| Collect company information | Day 1 |
| Review Form SS-4 | Day 2 |
| Submit application by fax | Day 3 |
| Allow for IRS processing | Generally around 4 business days for fax applications |
| Check the EIN notice and company records | After receiving the IRS response |
Phone applications may result in an EIN being assigned during the call if the IRS can process the request. Mail applications can take approximately four weeks. The actual time depends on the application method and IRS processing.
7. What Happens After Receiving the EIN?
After receiving an EIN, ABC Technologies should check that the company name and other details match its application. It should also save the IRS EIN assignment notice with its tax records.
The next step is to review the U.S. client's tax documentation request.
For a foreign corporation that is the beneficial owner of the income, Form W-8BEN-E may be the appropriate withholding certificate. The company should complete the treaty section only if it qualifies for the claimed benefit.
What Should the Company Check Before Claiming Treaty Benefits?
- Whether it is a tax resident of India under the treaty.
- Whether it is the beneficial owner of the payment.
- Whether the payment is a royalty, fee for included services, business profit, or another type of income.
- Whether it meets applicable limitation-on-benefits conditions.
- Whether it needs to provide a U.S. or foreign taxpayer identification number.
The correct tax form depends on the legal entity and who owns the income. A foreign company should not use an individual Form W-8BEN when Form W-8BEN-E is required.
8. Common Mistakes Foreign Companies Should Avoid
Foreign companies can face delays or incorrect withholding when they provide incomplete or inconsistent tax information.
- Assuming an EIN guarantees treaty benefits: An EIN does not prove that the company qualifies for a reduced tax rate.
- Choosing the wrong SS-4 purpose: The reason for applying must match the company's actual circumstances.
- Listing a nominee as the responsible party: The IRS generally requires an individual who actually owns or controls the entity.
- Using the wrong W-8 form: Foreign corporations generally use Form W-8BEN-E when documenting their own foreign status and claiming applicable treaty benefits.
- Giving incorrect company details: The legal name and address should match the company's records.
- Assuming all U.S. payments receive the same tax treatment: Different types of income can have different tax rules.
9. Key Lessons From This Indian Company EIN Case Study
This example shows that an Indian company can apply for a U.S. EIN without forming a U.S. company. However, it must have a valid reason for obtaining the number and follow the IRS application process.
The main lessons are:
- Prepare accurate company and responsible-party information before applying.
- Use Form SS-4 to request the EIN.
- Use an international application method if the company's principal place of business is outside the United States.
- Complete the treaty-related sections of Form W-8BEN-E only when the company qualifies.
- Keep the EIN assignment notice and tax documents safely.
- Check the U.S.–India treaty rules for the specific type of income.
10. Frequently Asked Questions
Can an Indian company get a U.S. EIN?
Yes. An Indian company can apply for a U.S. EIN directly through the IRS if it has a valid business or tax-related reason. It does not always need to form a U.S. company first.
Does an Indian company need a U.S. EIN to claim tax treaty benefits?
A U.S. or foreign taxpayer identification number may be required for a treaty claim. The exact requirement depends on the income and applicable IRS rules. An EIN alone does not establish treaty eligibility.
Can an Indian company apply for an EIN online?
Generally, no, if its principal place of business, office, or agency is outside the United States and its territories. It can use the international phone, fax, or mail application methods.
What is the IRS phone number for international EIN applications?
The IRS international EIN phone number is 267-941-1099. It is not toll-free. Check the current IRS instructions for service hours before calling.
How long does it take an Indian company to receive an EIN?
The time depends on the application method. The IRS generally states around four business days for fax applications and approximately four weeks for mail applications. A phone application may be processed during the call.
Which W-8 form should an Indian company submit?
An Indian corporation that is the beneficial owner of the income will generally use Form W-8BEN-E. The correct form can differ for partnerships, disregarded entities, intermediaries, and other structures.
Does an EIN reduce U.S. withholding tax automatically?
No. The company must qualify under the applicable tax rules and provide the correct withholding documentation. The U.S. payer must review the treaty claim before applying a reduced rate.
Conclusion
This foreign company EIN case study explains how an Indian company might prepare Form SS-4 and apply for a U.S. EIN for tax documentation purposes. The process starts with accurate company information, a valid application reason, and the correct responsible party.
However, obtaining an EIN is only one part of the process. An Indian company must separately check the U.S.–India tax treaty, its income type, beneficial ownership, and the correct W-8BEN-E requirements before claiming a reduced withholding rate.
For current application rules, always review the official IRS instructions or speak with a qualified international tax professional.